PensionBox BlogsDo You Know About TDS On Salary: Section 192

Do You Know About TDS On Salary: Section 192
03 Oct 2026 • 6 min read
Written By
Vaishnavi Verma
Vaishnavi Verma
PensionBox

TDS on salary is a frequently heard term by all. TDS stands for Tax Deducted at Source. Do you know about TDS on salary: Section 192? If not, we come to your rescue. To start with, let's understand TDS on Salary more simply. When you are looking for a job and you go through the company's offerings, you find the company proposing a certain CTC (Cost to Company), however, once you start working and receive your first salary, you notice that the salary you receive in hand in actually lower than the CTC which was earlier projected to you. Why is that so? Here's where TDS on Salary comes into the picture. Tax is deducted from your salary before you receive it in your hands. This is known as TDS on salary, i.e. Tax Deducted at Source on Salary.

In the Income Tax Act 1961, there's a section that is concerned with TDS on salary. Section 192 of the Income Tax Act is given responsibility for dealing with TDS on salary. Under this blog, we have covered all that you need to know about TDS on salary: Section 192.

Who is authorized to deduct TDS on Salary: Section 192?

TDS on Salary: Section 192 is an unavoidable feature when it comes to employers who pay salaries to their employees. The employee can be a resident or a non-resident. But it is mandatory on the part of the employer to deduct TDS on salary every month as provided by Section 192. An employer-employee relationship, in whichever arena, whether private or public, gives rise to the condition of TDS on Salary.

Who is the employer here?

The employer can be:-

    1. Firm
    1. Private or Public Company
    1. Trusts
    1. HUFS
    1. Cooperative Societies
    1. Individuals
    1. AOP, BOI

When is TDS on Salary deducted under Section 192?

TDS on Salary under Section 192 of the Income-tax Act requires the deduction of tax when-

    1. The employer makes payment to the employee.
    1. The payment made by the employer to the employee must be like the salary provided to the employee.
    1. The income of the employee is above the amount to which tax is not levied.
    1. TDS will be deducted no matter if the employer pays the salary in advance on time or late.
    1. TDS will be deducted even if the employee does not possess a PAN.
    1. Exemption limits on age limits to which TDS is non-deductible are-
  • a. ₹2.5 Lakh- Residents below the age of 60 (these three limits apply only under the old tax regime; under the default new tax regime, tax is nil up to ₹4 lakh, and the Section 87A rebate means no tax up to ₹12 lakh of taxable income, or ₹12.75 lakh for salaried employees).
  • b. ₹3 Lakh- Senior Citizens aged between 60 years and 80 years.
  • c. ₹5 Lakh- Above 80 years

Steps to calculate TDS on salary: Section 192

    1. The salary of the employee is calculated for the given financial year. The salary would be a cumulative sum of basic pay along with all the other relevant allowances like Dearness Allowance, HRA, Travelling Allowances, House Rent Allowance, LTA, Employee Provident Fund contribution, bonuses, gratuity, commissions, and any other applicable allowances.
    1. Exemptions under Section 10 of the Income Tax Act would be calculated to find if any of them applies to the employee. For instance, exemptions can apply to education allowances, medical allowances, housing rent allowances, travel allowances, etc. The third step includes deducting the applicable exemption from the monthly income and the obtained net amount will be considered as the taxable salary.

-3. The employer needs to deduct any investment that comes under Chapter IV-A of the Income Tax Act. The investment may be in the form of an Employee's Provident Fund, PPF, NSC, ELSS, home loan repayment, education loan repayment, or any other deduction falling into Section 80D, Section 80G, etc of the Income-tax Act.

Rate of TDS on Salary: Section 192

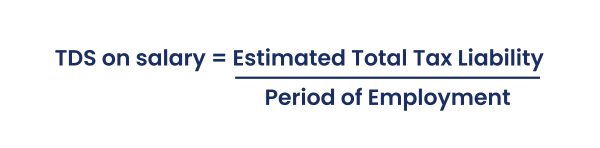
There's no specified rate of TDS on salary given by Section 192 of the Income Tax Act. To calculate the rate of TDS on salary, the estimated total income of the employee is taken into consideration which has been earned during that particular financial year. The Income tax slab is taken as the basis for calculating the income of employees which is taxable under the Income Tax Act.
TDS on salary deduction in the case of multiple employers

One might think that calculating TDS on salary in the case of multiple employers would turn out to be a hassle. Let's evaluate the situations in which a need may arise to calculate TDS on salary in the case of multiple employers:

  • 1. Simultaneously involved with two or more employers- When an employee is simultaneously involved with two or more employers, in such a case the employee is required to submit details of his salary and TDS in the FORM 12B to either one of the employers. Then one of the employers would deduct TDS from the salary. For instance, Arun is simultaneously involved with two employers. He is employed by Asha Ltd. and London Waffle Private Ltd. He may then choose out of the two, which company/employer would perform a TDS deduction on his aggregate salary.

  • 2. Changing job during the year- If a person has changed jobs during a financial year, he/she is required to provide the details and whereabouts of previous employment given in Form 12B to the current employer. The new employer will then consider the previous salary and the applied TDS while calculating TDS for the remaining months.

What is the time limit to deposit TDS on salary: Section 192

The employer is required to deposit TDS on salary, or Tax Deducted at Source on salary to the government at the time of payment of salary to the employee. The following dates must be followed to avoid interest:

    1. TDS on salary deducted for March: 30th April.
    1. TDS on salary deducted for April- February: 30 April

Consequences of Non-Compliance under Section 192

  • 1. Levy of Interest- An interest of 1.5% will be levied on the amount in case the employer fails to deduct TDS on salary. The interest of 1.5% will also be applied if the employer deducts the TDS but fails to deposit it to the government.

  • 2. Disallowance of Expenses- If TDS on salary is not deducted as per regulations on time, the employer cannot claim a deduction of salary expense from the profits and gains.

  • 3. The amount of disallowed salary expenses will be

  • a. 30% of salary payment will go to residents.

  • b. 100% of salary payment will go to Non-Resident

PensionBox aims at simplifying complex terms like TDS on Salary and Section 192 so that every individual becomes aware. Become a part of Pension Box and stay up to date with everything regarding TDS on salary!

Frequently asked questions

How is TDS on Salary calculated under Section 192?

TDS on Salary is calculated based on the employee's income, exemptions, deductions, and the applicable tax slab rates. Employers use the income details provided by employees to calculate the TDS amount as per the rates specified in Section 192. Addit

What are the responsibilities of employers and employees regarding TDS on Salary under Section 192?

Employers are responsible for deducting TDS on Salary as per the rates specified in Section 192 and depositing the deducted amount with the government within the stipulated time frame. They must also provide Form 16 to employees, which details the TD

You find the blog helpful, spread it among your peers
If you find anything to share regarding this specific blog, write us here
support@pensionbox.in
Published By
PensionBox

Related articles

What is self assessment tax?
The question,“What is self-assessment tax” has been answered in detail in this blog. It is extremely important to understand what is self-assessment tax or SAT, because first of all, taxes are an unavoidable entity. You have to pay taxes no matter what. Every individual is required to be updated with financial knowledge, especially related to taxes to attain financial stability and minimize tax liabilities. It must be noted that taxpayers who need to fill out their Income Tax Return or ITR have to pay this tax in advance.
08 Oct 2026
Tips help last minute taxpayers
If you are a procrastinator and always take the work to the last minute, there are high chances you pay taxes at the last minute too! The process of paying taxes may seem like a hassle to many. Firstly, you must gather all the documents required to file for Income Tax Returns or ITR, which sounds like a struggle. Then, you need to sit with all the documents and go through the online tax payment process. If you are planning to physically go and pay taxes, it might further seem like an inconvenience and you would keep delaying the process until the deadline comes close. This guide will provide tips that would help last-minute taxpayers go through the tax payment process efficiently. Tips for last-minute tax planning have also been included so that taxpayers can minimize tax liabilities.
03 Oct 2026
Know The Tax Saving Options Available Only To Women
It is absolutely important to know the tax-saving options available only to women, especially in India, where women don't have sufficient knowledge about finances. Shockingly, a major chunk of women are not even in possession of bank accounts. Not to deny that the condition of women in the financial aspect is better than what it used to be, however, more and more women need to take a step ahead and participate in financial planning.
03 Oct 2026
Simplfying The Ways Of Tax Saving
Taxes are an unavoidable part of life for everyone. For many people, the topic of taxes can be a confusing and intimidating one. India is no different and the tax system there can be complex and hard to understand. Fortunately, there are ways to minimise your tax burden and save money.
03 Oct 2026
One Vision,
2,00,000+ Stories
Every time we hear a new story, it inspires us.
Hope they inspires you as well.
"Very intuitive and smooth experience with the app. Helps me start planning my savings and retirement in a super easy manner which I assumed might be difficult thing to do."
Anjali Agarwal
PensionBox User
"Saving is an essential part of any employee’s life. With this integration, our HRMS users can directly invest and track their pension funds straight from their ESS portals, making the process seamless."
Jitendra Somani
CEO, Pocket HRMS
"Runtime HRMS is built with a vision to Create Happier Workplaces for the working population of India, and it neatly aligns with PensionBox’s vision to create financial freedom for people during and beyond their work-life."
Prashant Agarwal
Founder, Runtime Software
"Easy to use and smooth user interface. Pensionbox developers deserve praise. People can plan their retirement in advance with this tool. Keep up the good work guys, looking forward for some more features added to the list."
Sourabh Mishra
PensionBox User
"One of the few apps that solves the problem of tracking and investing of my retirement Corpus. Ul is sleek, customer care is great and full marks for bug free experience"
Prashant jain
User since 7 months
"PensionBox addresses a very important need for billions of Indians who do not have access to the right resources to make an informed choice and then continue to track their funds easily."
Ninad Karpe
Founder VC, 100x.VC
avatar
Over 1.8 crore users have already created
their NPS stories for a golden retirement.
News & Articles
inc42
yourStory
economicTimes
entrackr
moneycontrol
ndtv
Frequently asked questions
PensionBox is India’s first pension platform/app that helps you access, invest in, and track your NPS and other pension products with better user experience & minimum charges.

PensionBox simplifies the National Pension System(NPS), the government's pension scheme for private employees both for retail users and HRs/companies.

If you don’t have an NPS account, you can simply open your pension account within 2 minutes and if you have NPS PRAN already, you will be able track, invest and manage everything free of charge with best user experience.
Absolutely. PensionBox is fully ISO 27001 compliant with the Pension Fund Regulatory and Development Authority (PFRDA), the government body that regulates pensions in India.

We never touch or hold your money directly, your investments go safely to your chosen pension fund through approved channels.

We are built with Zerodha as POP , ensuring transparency, data security, and peace of mind. Your retirement savings are protected by regulation and secured by technology.
Banks/POPs charges high fees on account opening & every investment Even CRA apps have hidden charges/low transparency & lack timely support Pension Funds restrict pension fund choice & selection to themselves.

That’s why, PensionBox brings transparency, zero charges, timely support and freedom to select any pension fund so that you get the best experience investing in NPS & be better future ready.

That’s not it, we help you & your company together to maximise contribution and tax savings with minimal charges & best user experience.
It’s super easy to use PensionBox, just start by signing up using your browser on laptop/mobile or downloading the app on appstore or playstore.

If you are an existing zerodha user then you get a fast login or sign up using kite ID.

Once you are onboarded with kite ID, you get free access to
  • Open NPS in 2 minutes
  • Track existing NPS
  • POP shift or CRA shifting
  • Invest in one time or create SIP in NPS
  • Withdraw NPS requests & instant withdraw tier 2
  • Create your dream retirement plan
  • Open NPS Vatsalya for your kid
  • Share with HR (To unlock more tax benefits)
Tax Benefits in New Tax Regime
  • Employer Contribution:
    • Contributions made by your employer to your NPS account are tax-free up to 14% of your basic salary under Section 80CCD(2). Do connect us with your HR to enable this for you.
    Tax Benefits in Old Tax Regime
  • Self-Contribution:
    • Deduction up to ₹1.5 lakh under Section 80C.
    • Additional deduction of ₹50,000 under Section 80CCD(1B) — exclusive to NPS investments!
    • This allows you to claim a total deduction of up to ₹2 lakh every year on your NPS contributions.
  • Employer Contribution:
    • Contributions made by your employer to your NPS account are tax-free up to 10% of your basic salary (Basic + DA) under Section 80CCD(2). Do connect us with your HR to enable this for you.
    • This is over and above your personal deduction limits, giving you extra tax efficiency.
We understand NPS can be confusing, complex and there is a lot of information out there to believe in. Don’t worry, our team is here to help you with the right information.

Feel free to book a free call to learn more about NPS, NPS Vatsalya, Corporate NPS & PensionBox or contact the support team.
Blogs

PensionBox is registered trademark managed & owned by Asht Capital Private Limited. CIN -U67190UP2021PTC142016. All Rights Reserved.

PensionBox is India’s first pension startup for the private employed workforce. PensionBox is ISO 27001 certified and approved by PFRDA for the National Pension System. Recognized as a startup by the Department for Promotion of Industry and Internal Trade, Certificate under StartupIndia Initiative DIPP80990 & StartinUP Initiative. Incubated & supported by UPES Council for Innovation and Entrepreneurship (UCIE).

PensionBox works as Technology Platform/Partner with Zerodha Broking Limited, Point of Presence (POP) as Pension Agent under PFRDA (PoP) Regulations 2023 to enable NPS account opening, transacting funds, manage account under All Citizen and Corporate NPS in India.

Grievance Redressal as per Regulation 31 of PFRDA (Redressal of Subscriber Grievance) Regulations, 2015:
The details of the Ombudsman appointed are available on the PFRDA website - www.pfrda.org.in At present, Shri Narender Kumar Bhola has been appointed as the new Ombudsman in terms of the PFRDA (Redressal of Subscriber Grievance) Regulations, 2015.


Details of the ombudsman are as under:

Shri Narender Kumar Bhola
Pension Fund Regulatory and Development Authority
B-14/A, Chatrapati Shivaji Bhawan,
Qutab Institutional Area, Katwaria Sarai, New Delhi- 110016
Chhatrapati Shivaji Bhawan,
Id: ombudsman@pfrda.org.in
Landline No.: 011 - 26517507 Ext : 188
Grievance Redressal Officer
Name: Aiman Bashir
Email: aiman@pensionbox.in
Name: Kuldeep Parashar
Email: kuldeep@pensionbox.in
Phone: +91 80 6558 8333

Registered Office Address: Asht Capital Private Limited, House 2, Vaishali Puram, Firozabad Road, Tundla, Uttar Pradesh, 283204
Bangalore Office Address: First Floor, 680, 15th Cross Rd, Jeewan Griha Colony, 2nd Phase, J. P. Nagar, Bengaluru, Karnataka 560078 | support@pensionbox.in | +91 80 6558 8333

Copyright ©2026 PensionBox, All rights reserved.