


Income Tax Slabs FY 2023-24 and AY 2024-25

The income slab rates under the New Tax Regime and the Old Tax Regime are different. This difference has given a distinction between the Old and New Tax regime. , even the exemptions, allowances, and deductions under the Old and the New tax regime are different from each other. Not all exemptions, allowances, and deductions are available under both of the tax regimes. It is to be noted that if one of the two tax regimes, i.e. Old tax regime or New tax regime is not opted by the employee, the taxes will automatically be computed under the New tax regime by default.
Having understood how the New tax regime and the Old tax regime are different from each other, let's move forward to learn more about Income Tax Slabs FY 2023-24 & AY 2024-25 (New & Old Regime Tax Rates)
What is an Income Tax Slab?
Income tax in India is the tax levied on the income of an individual. The salary that you earn is what the tax is chargeable upon, given that it exceeds the exemption level. This tax is applied based on your income level, or income range. Different tax slabs are associated with different ranges of income. The income slab keeps changing from time to time. This means that as your income keeps increasing, the income tax rate also increases. Those who earn more pay more income tax, which only seems fair. A progressive taxation system is established through the system of Income Tax Slabs.
Generally, during the Budget every financial year, the Income-tax slabs are revised, hence generating a system wherein the slab rates differ for different income groups.
Slab rates under the Old Tax Regime are dissected into these categories:
-
- Residents of India in the age group- Above 60 years + All Non Residents
-
- Resident Senior Citizens in the age group- 60-80 years
-
- Resident Super Senior Citizens in the age group- Above 80 years
Income Tax Slabs FY 2023-24 & AY 2024-25 (New & Old Regime Tax Rates)
Old Tax Regime-
For those opting for the Old Tax Regime, a tax rebate of ₹12,500 is applied, given that the total income of the taxpayer does not exceed ₹5 lakh. It must be noted that this does not apply to Non-Resident Indians
The income tax exemption limit for the old tax regime is-
-
- ₹2,50,000 for individuals below 60 years of age, as well as all Non-residents
-
- ₹3,00,000 for senior citizens in the age group 60-80 years
-
- ₹5,00,000 for super senior citizens above 80 years
CESS & Surcharges will apply to the tax rates.
New Tax Regime-
For those opting for the New Tax Regime, a tax rebate of ₹25,000 is applied, given that the total income of the taxpayer does not exceed ₹7 lakh. It must be noted that this does not apply to Non-Resident Indians
The income tax exemption limit for the new tax regime is-
-
- ₹3,00,000 for individuals, HUFs
CESS & surcharges will be applicable on the tax rates.
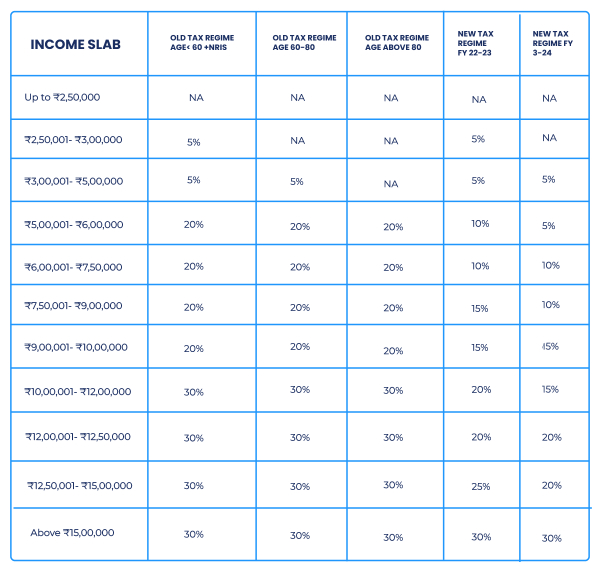
Let's understand Income Tax Slabs FY 2023-24 under the Old Tax Regime and New Tax Regime through the tabular data given below-
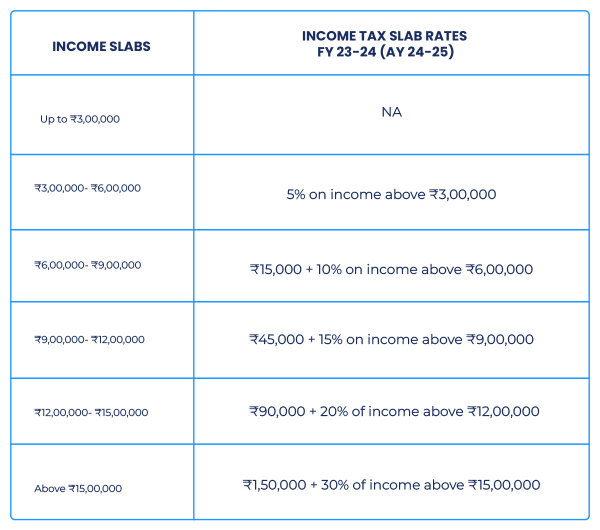
Revised Income slab rate AY 24-25 for those who opt for the New tax regime-
Notable changes in the filing of Income tax return (ITR) from FY 22-23 to FY23-24
-
- In FY 22-23, the Old tax regime was the default one. So, if you want to switch to the New Tax regime from the Old one, you must fill out and submit Form 10IE. Having failed to do that before the due date, you were automatically required to file under the Old tax regime only.
-
- In FY 23-24, the opposite was mandated. Here, the default regime was changed to a New tax regime. Now, if you want to opt for the Old tax regime, you must file it before the due date. If you fail to do so, you will automatically be required to file under the New tax regime. This would mean that you would have to give up your claim on deductions and exemptions from the Old tax regime.
Few important things to keep in mind if you opt for a New tax regime
-
- The income tax slab rates for all categories of individuals, i.e. individuals 60 years, senior citizens, and super senior citizens, are the same under the New tax regime.
-
- All individuals with net income less than or equal to ₹7,00,000 will be eligible for tax rebate as per Section 87A. This means that tax liability will be NIL.
This blog focused on Income Tax Slabs FY 2023-24 & AY 2024-25 (New & Old Regime Tax Rates) and an attempt was made by PensionBox to provide basic information about Income tax slab rates, how they differ under the Old tax regime and the New tax regime, what are the current slab rates and other related information to the taxpayers.

PensionBox simplifies the National Pension System(NPS), the government's pension scheme for private employees both for retail users and HRs/companies.
If you don’t have an NPS account, you can simply open your pension account within 2 minutes and if you have NPS PRAN already, you will be able track, invest and manage everything free of charge with best user experience.
We never touch or hold your money directly, your investments go safely to your chosen pension fund through approved channels.
We are built with Zerodha as POP , ensuring transparency, data security, and peace of mind. Your retirement savings are protected by regulation and secured by technology.
That’s why, PensionBox brings transparency, zero charges, timely support and freedom to select any pension fund so that you get the best experience investing in NPS & be better future ready.
That’s not it, we help you & your company together to maximise contribution and tax savings with minimal charges & best user experience.
If you are an existing zerodha user then you get a fast login or sign up using kite ID.
Once you are onboarded with kite ID, you get free access to
- Open NPS in 2 minutes
- Track existing NPS
- POP shift or CRA shifting
- Invest in one time or create SIP in NPS
- Withdraw NPS requests & instant withdraw tier 2
- Create your dream retirement plan
- Open NPS Vatsalya for your kid
- Share with HR (To unlock more tax benefits)
- Employer Contribution:
- Contributions made by your employer to your NPS account are tax-free up to 14% of your basic salary under Section 80CCD(2). Do connect us with your HR to enable this for you.
Tax Benefits in Old Tax Regime - Self-Contribution:
- Deduction up to ₹1.5 lakh under Section 80C.
- Additional deduction of ₹50,000 under Section 80CCD(1B) — exclusive to NPS investments!
- This allows you to claim a total deduction of up to ₹2 lakh every year on your NPS contributions.
- Employer Contribution:
- Contributions made by your employer to your NPS account are tax-free up to 10% of your basic salary (Basic + DA) under Section 80CCD(2). Do connect us with your HR to enable this for you.
- This is over and above your personal deduction limits, giving you extra tax efficiency.
Feel free to book a free call to learn more about NPS, NPS Vatsalya, Corporate NPS & PensionBox or contact the support team.





