


NPS with PensionBox and Where does your money go?

Planning for retirement can be overwhelming, but with PensionBox, your journey toward financial freedom becomes seamless. PensionBox stands out as the most trusted pension platform, dedicated to simplifying the process of planning, tracking, investing, and more in your retirement goals.
PensionBox understands the value of your time, and that's why we've streamlined the process of opening an NPS (National Pension Scheme) account in just 3 minutes. The entire process is hassle-free and conducted seamlessly online, eliminating unnecessary paperwork and delays.
Understanding NPS Structure
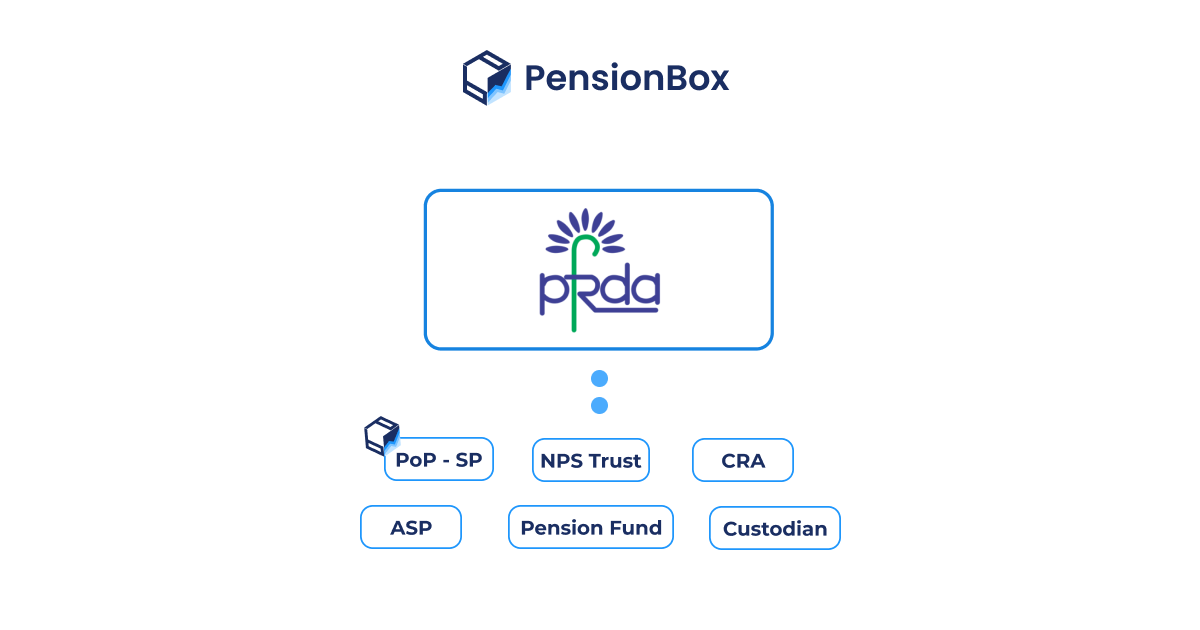
PFRDA (Pension Fund Regulatory & Development Authority of India) has set up a streamlined system with specialised intermediaries managing tasks like recordkeeping, fund transfers, fund management, and custodial services. This approach ensures that each aspect of the process is handled by experts, promoting effective checks and balances for the subscribers.
-
The Central Recordkeeping Agency (CRA), is responsible for keeping track of subscriber’s data and acts as a bridge among other intermediaries.
-
Points of Presence (PoP) and POP-Service Providers (PoP-SP) such as PensionBox, are also regulated by PFRDA, serving as the initial points of contact for NPS subscribers. Authorized branches of a PoP, known as Point of Presence Service Providers (PoP-SPs), function as collection points and provide a variety of customer services to NPS subscribers.
-
NPS Trust & Trustee Bank- The NPS Trust, formed by the PFRDA, manages funds in the NPS. It keeps its funds in a bank account, known as the 'Trustee Bank.' This bank sends money to Pension Funds (PFs), Annuity Service Providers (ASPs), and subscribers based on instructions from CRAs.
-
Pension Funds (PF)- These are selected to manage the Pension Fund contributions across multiple schemes for all subscribers
-
Annuity Service Providers (ASP)- These insurance firms are overseen by IRDA and authorized by PFRDA to invest people's retirement savings in an Annuity plan. They ensure monthly pension payouts to the subscriber.
-
Custodian- Stock Holding Corporation of India Limited is chosen as a Custodian to offer custodial services for the NPS.
Where does your money go?
The money you put into your pension account, your respective PoP-SP transfers your funds to be handled by Pension Fund Managers registered with PFRDA.
These managers follow rules set by PFRDA to invest the funds wisely. They make sure to spread the investments across different types of financial assets, like government securities, corporate bonds, and stocks. This diversification helps protect your savings, even if the market goes through a tough time. Currently, subscribers have the choice of 8 Pension Fund Managers to look after their money based on their preference.
Following are the PFMs available for subscribers to choose from-
- Birla Sunlife Pension Management Limited
- HDFC Pension Management Company Limited
- ICICI Prudential Pension Funds Management Company Limited
- Kotak Mahindra Pension Fund Limited
- LIC Pension Fund Limited
- SBI Pension Funds Private Limited
- UTI Retirement Solutions Limited
Investment choices under NPS
Under NPS, there are 8 Pension Fund Managers (PFMs), investment choices (Auto or Active), and 4 types of assets: Stocks, Corporate Bonds, Government Bonds, and Alternative Investment Funds. Subscribers need to first pick a PFM, after which they can then decide on their preferred Investment Option.
1. Active choice: Individual Funds
In this investment option, the Subscriber has the freedom to personally choose how their money is invested. The Subscriber needs to inform the Pension Fund Manager (PFM) about the Asset Class (like stocks or bonds) and the percentage they want to allocate to each scheme offered by the PFM.
There are four Asset Classes available (Equity, Corporate debt, Government Bonds, and Alternative Investment Funds), and the Subscriber specifies how their investment should be distributed within a single PFM.
- Asset Class E involves investments in stocks and related instruments
- Asset Class C focuses on corporate debt and related instruments.
- Asset Class G on the other hand, deals with government bonds and related instruments.
- Asset Class A encompasses alternative investment funds, which include various instruments such as CMBS, MBS, REITS, AIFs, Invlts, and more.
Subscribers have the option to choose various types of investments within a single Pension Fund Manager (PFM). For those aged up to 50 years, the highest allowed investment in stocks is 75% of the total investment. For individuals aged 51 and above, the maximum allowed stock investment is determined by a provided matrix, which takes into account the subscriber's date of birth.
Additionally, contributions to Alternative Investment Funds cannot surpass 5%. It's important to note that the total investment across different asset classes (Equity, Corporate Bonds, Government Securities, and Alternative Investment) must add up to 100%
2. Auto choice: Lifecycle Funds
For Subscribers who may not feel confident managing their NPS investments, there's a simple solution. They can choose the Auto Choice option, where the investments are handled in a life-cycle fund. This fund adjusts the proportion of money invested in three types of assets based on the Subscriber's age.
It's a great choice for those who want to automatically decrease exposure to riskier investments as they get older. As individuals age, their involvement in Equity and Corporate Debt tends to decrease. The 'Auto Choice' option offers 3 variations – Aggressive, Moderate, and Conservative – allowing Subscribers to pick the one that matches their risk tolerance.
-
LC75 - Dynamic Life Cycle Fund: This fund limits 75% of the total assets for investing in stocks. The involvement in stocks kicks off at 75% until the subscriber reaches 35 years of age, gradually decreasing based on the subscriber's age.
-
LC50 - Moderate Life Cycle Fund: This fund limits equity investments to 50% of the total assets. It begins with a 50% exposure to equity investments until the subscriber reaches 35 years of age, gradually decreasing as the subscriber gets older.
-
LC25 - Conservative Life Cycle Fund: This fund has a maximum limit of 25% for investing in stocks. The investment in stocks begins at 25% when you're 35 years old and decreases gradually as you get older.
Be assured that your contributions to NPS through PensionBox are processed the fastest and secured. Our regulation by PFRDA directly ensures the safety of your money and guarantees your privacy with encrypted data. Moreover, you enjoy increased tax exemptions on your contributions. At PensionBox, transparency and trust are core values, ensuring no hidden fees or charges.

PensionBox simplifies the National Pension System(NPS), the government's pension scheme for private employees both for retail users and HRs/companies.
If you don’t have an NPS account, you can simply open your pension account within 2 minutes and if you have NPS PRAN already, you will be able track, invest and manage everything free of charge with best user experience.
We never touch or hold your money directly, your investments go safely to your chosen pension fund through approved channels.
We are built with Zerodha as POP , ensuring transparency, data security, and peace of mind. Your retirement savings are protected by regulation and secured by technology.
That’s why, PensionBox brings transparency, zero charges, timely support and freedom to select any pension fund so that you get the best experience investing in NPS & be better future ready.
That’s not it, we help you & your company together to maximise contribution and tax savings with minimal charges & best user experience.
If you are an existing zerodha user then you get a fast login or sign up using kite ID.
Once you are onboarded with kite ID, you get free access to
- Open NPS in 2 minutes
- Track existing NPS
- POP shift or CRA shifting
- Invest in one time or create SIP in NPS
- Withdraw NPS requests & instant withdraw tier 2
- Create your dream retirement plan
- Open NPS Vatsalya for your kid
- Share with HR (To unlock more tax benefits)
- Employer Contribution:
- Contributions made by your employer to your NPS account are tax-free up to 14% of your basic salary under Section 80CCD(2). Do connect us with your HR to enable this for you.
Tax Benefits in Old Tax Regime - Self-Contribution:
- Deduction up to ₹1.5 lakh under Section 80C.
- Additional deduction of ₹50,000 under Section 80CCD(1B) — exclusive to NPS investments!
- This allows you to claim a total deduction of up to ₹2 lakh every year on your NPS contributions.
- Employer Contribution:
- Contributions made by your employer to your NPS account are tax-free up to 10% of your basic salary (Basic + DA) under Section 80CCD(2). Do connect us with your HR to enable this for you.
- This is over and above your personal deduction limits, giving you extra tax efficiency.
Feel free to book a free call to learn more about NPS, NPS Vatsalya, Corporate NPS & PensionBox or contact the support team.





