eNPS to PoP: how to shift your NPS account and what it costs in 2026
The National Pension System (NPS) is a voluntary, market-linked retirement savings scheme, regulated by PFRDA, where you invest during your working years to build a pension corpus.
Opened your NPS account online through eNPS and now want better tracking, easier SIPs and real support? You're not alone. Many subscribers start on eNPS and later look for a platform that does more.
Shifting from eNPS to a PoP keeps your PRAN, your units and your history. You ask the new PoP to take over your account; on PensionBox you give consent in the app and our team completes it. The move is one-way: you can switch PoPs later, but you cannot go back to eNPS.
How to invest in NPS: through a CRA or a PoP
There are two ways to open and run an NPS account. Both give you the same PRAN, the same pension funds and the same investment options. What differs is who you deal with and how much help you get.
Investing through a CRA (eNPS)
A Central Recordkeeping Agency (CRA) keeps the records for every NPS account. The CRAs are Protean, KFintech and CAMS. When you open your account online on a CRA's own eNPS website, you are investing through the CRA route.
Implications of investing through a CRA (eNPS)
- Lower platform cost. Subscribers onboarded through eNPS who keep contributing via eNPS or D-Remit don't pay PoP charges.
- More work on your side. You handle the portal, forms and service requests yourself.
- Self-service support. There is no dedicated team to guide you through contributions or withdrawals.
- Open to moving later. You can shift to a PoP at any time, but it is a one-way move.
Investing through a PoP
A Point of Presence (PoP) is a registered intermediary, such as an app, bank or broker, that services your NPS account on top of the CRA. PensionBox works with Zerodha Broking, a PFRDA-registered PoP. Your account is still recorded with a CRA, but you do your day-to-day work in the PoP's app.
Implications of investing through a PoP
- PoP charges apply. A one-time onboarding charge and a 0.20% annual charge, plus 18% GST (details below).
- A simpler experience. One app for your account, SIPs and tracking, with human support when you need it.
- Same core costs as eNPS. CRA charges, fund management fees and NPS Trust charges are the same on both routes.
- Flexible within PoPs. You can switch between PoPs later, but you cannot go back to eNPS.
CRA vs PoP: comparison table
| Criteria | CRA route (eNPS) | PoP route (e.g. PensionBox with Zerodha) |
|---|---|---|
| Account opening & management | Online on the CRA's eNPS website | In the PoP's app, with digital KYC |
| Dashboard and tracking | Through the CRA portal | One app for Tier I and Tier II, PRAN tracking, plus NPS Vatsalya and EPF tracking |
| Support | Self-service | A support team you can speak to, including at withdrawal time |
| PoP charges | None, if you stay on eNPS and contribute via eNPS or D-Remit | ₹200 one-time (₹100 fully digital) and 0.20% a year, plus 18% GST, from 1 December 2026 |
| Switching later | Can move to a PoP, but not back | Can switch to another PoP, but not back to eNPS |
| Best for | Comfortable self-managers who want the lowest platform cost | People who want one simple app and a team to help |
Your PRAN, corpus, CRA charges and fund charges are the same either way.
What does eNPS to NPS migration mean?
You may see this searched as "convert eNPS to NPS". What you're really doing is moving your PRAN from the eNPS channel to a Point of Presence (PoP). Your PRAN, your units and your investment history stay the same. Only the channel that services your account changes.
What is the use of shifting from eNPS to NPS?
The main reason to shift is to get more than a contribution portal. eNPS is built for opening an account and paying contributions. A PoP gives you comprehensive portfolio tracking and responsive human support for your account.
- One dashboard for your retirement money. PensionBox lets you open Tier I and Tier II accounts, set up SIPs, track your PRAN and manage withdrawals, with NPS Vatsalya and EPF tracking supported as well.
- Easier SIPs. Set up and manage contributions without going back to a CRA portal each time.
- Guided support. Talk to a support team when you need help, instead of working through the process alone, including at withdrawal time. If you only want to pay contributions and don't need any of this, staying on eNPS is a valid choice.
NPS charges in 2026: what you pay and to whom
Your NPS costs fall into two groups. PoP charges are paid to the platform that services your account. CRA and pension fund charges are paid on every NPS All Citizen account, wherever it was opened, including eNPS.
1. NPS PoP charges (effective 1 December 2026)
| PoP charge | Amount | How it is collected |
|---|---|---|
| One-time onboarding (new account) | ₹200 standard. ₹100 for fully digital onboarding | Collected by the CRA by cancelling units, ₹50 a quarter, paid to the PoP after the quarter you were onboarded |
| Annual charge | 0.20% a year of the money in your account | Adjusted through the NAV, paid to the PoP every quarter |
| Each contribution (SIP or one-time) | No PoP charge | – |
| Dormant account | No annual charge | No contribution for four quarters in a row, across all NPS accounts under the same PAN |
| Withdrawal or exit | No PoP charge | The 2026 circular has no exit charge |
Additionally, GST of 18% is levied on these charges. On a ₹5 lakh corpus, the 0.20% annual charge works out to ₹1,000 a year before GST.
Once you shift to a PoP, PoP charges apply even if you later contribute through eNPS or D-Remit.
Source: PFRDA circulars PFRDA/2026/46/REG-POP/08 (28 August 2026, the charges) and PFRDA/2026/53/REG-POP/09 (26 October 2026, the new start date).
2. NPS CRA and pension fund charges (separate from PoP charges)
These are not PoP charges. Every NPS All Citizen account pays them, so they stay the same whether you remain on eNPS or shift to a PoP. They apply to the CRA that keeps your account (Protean, KFintech or CAMS).
How CRA charges are collected: CRA charges are deducted from your account by cancelling units. Fund manager and NPS Trust charges are built into the NAV, so you don't pay them separately.
From 1 July 2026, dormant accounts are charged one-tenth of the normal annual fee, and adding a new account tier to an existing PRAN stays free.
What this means in practice
Take a ₹5 lakh corpus with a standard-scheme fund fee at the upper end (0.12%). You can model your own corpus on the NPS calculator. Rough annual costs would be:
- NPS fund management charges: about ₹600, built into the NAV
- CRA annual maintenance: charged by corpus slab, as per your CRA's current schedule
- PoP annual charge (if you shift): 0.20%, about ₹1,000 The CRA and fund charges are the same on eNPS. The PoP charge is the main difference shifting adds. This is an illustration, not a quote, and it excludes per-transaction CRA charges, GST and one-time charges.
Position as of 30 October 2026. This is general information, not investment or tax advice.
What you get for the PoP charges
On a ₹5 lakh corpus, the 0.20% annual PoP charge is about ₹1,000 a year before GST, or roughly ₹83 a month. As the corpus grows, so does the charge:
| Corpus | 0.20% PoP charge a year | With 18% GST |
|---|---|---|
| ₹5 lakh | ₹1,000 | ₹1,180 |
| ₹10 lakh | ₹2,000 | ₹2,360 |
| ₹25 lakh | ₹5,000 | ₹5,900 |
| ₹50 lakh | ₹10,000 | ₹11,800 |
Here is what that pays for:
- One dashboard: your Tier I and Tier II accounts, PRAN, holdings and SIPs in a single app.
- Everything in one place: NPS Vatsalya and EPF tracking alongside your NPS account.
- SIPs without the portal: set up and manage contributions inside the app.
- A person to talk to: a support team, including when it is time to withdraw.
- No extra PoP charge on contributions, withdrawals or exits, and none on dormant accounts.
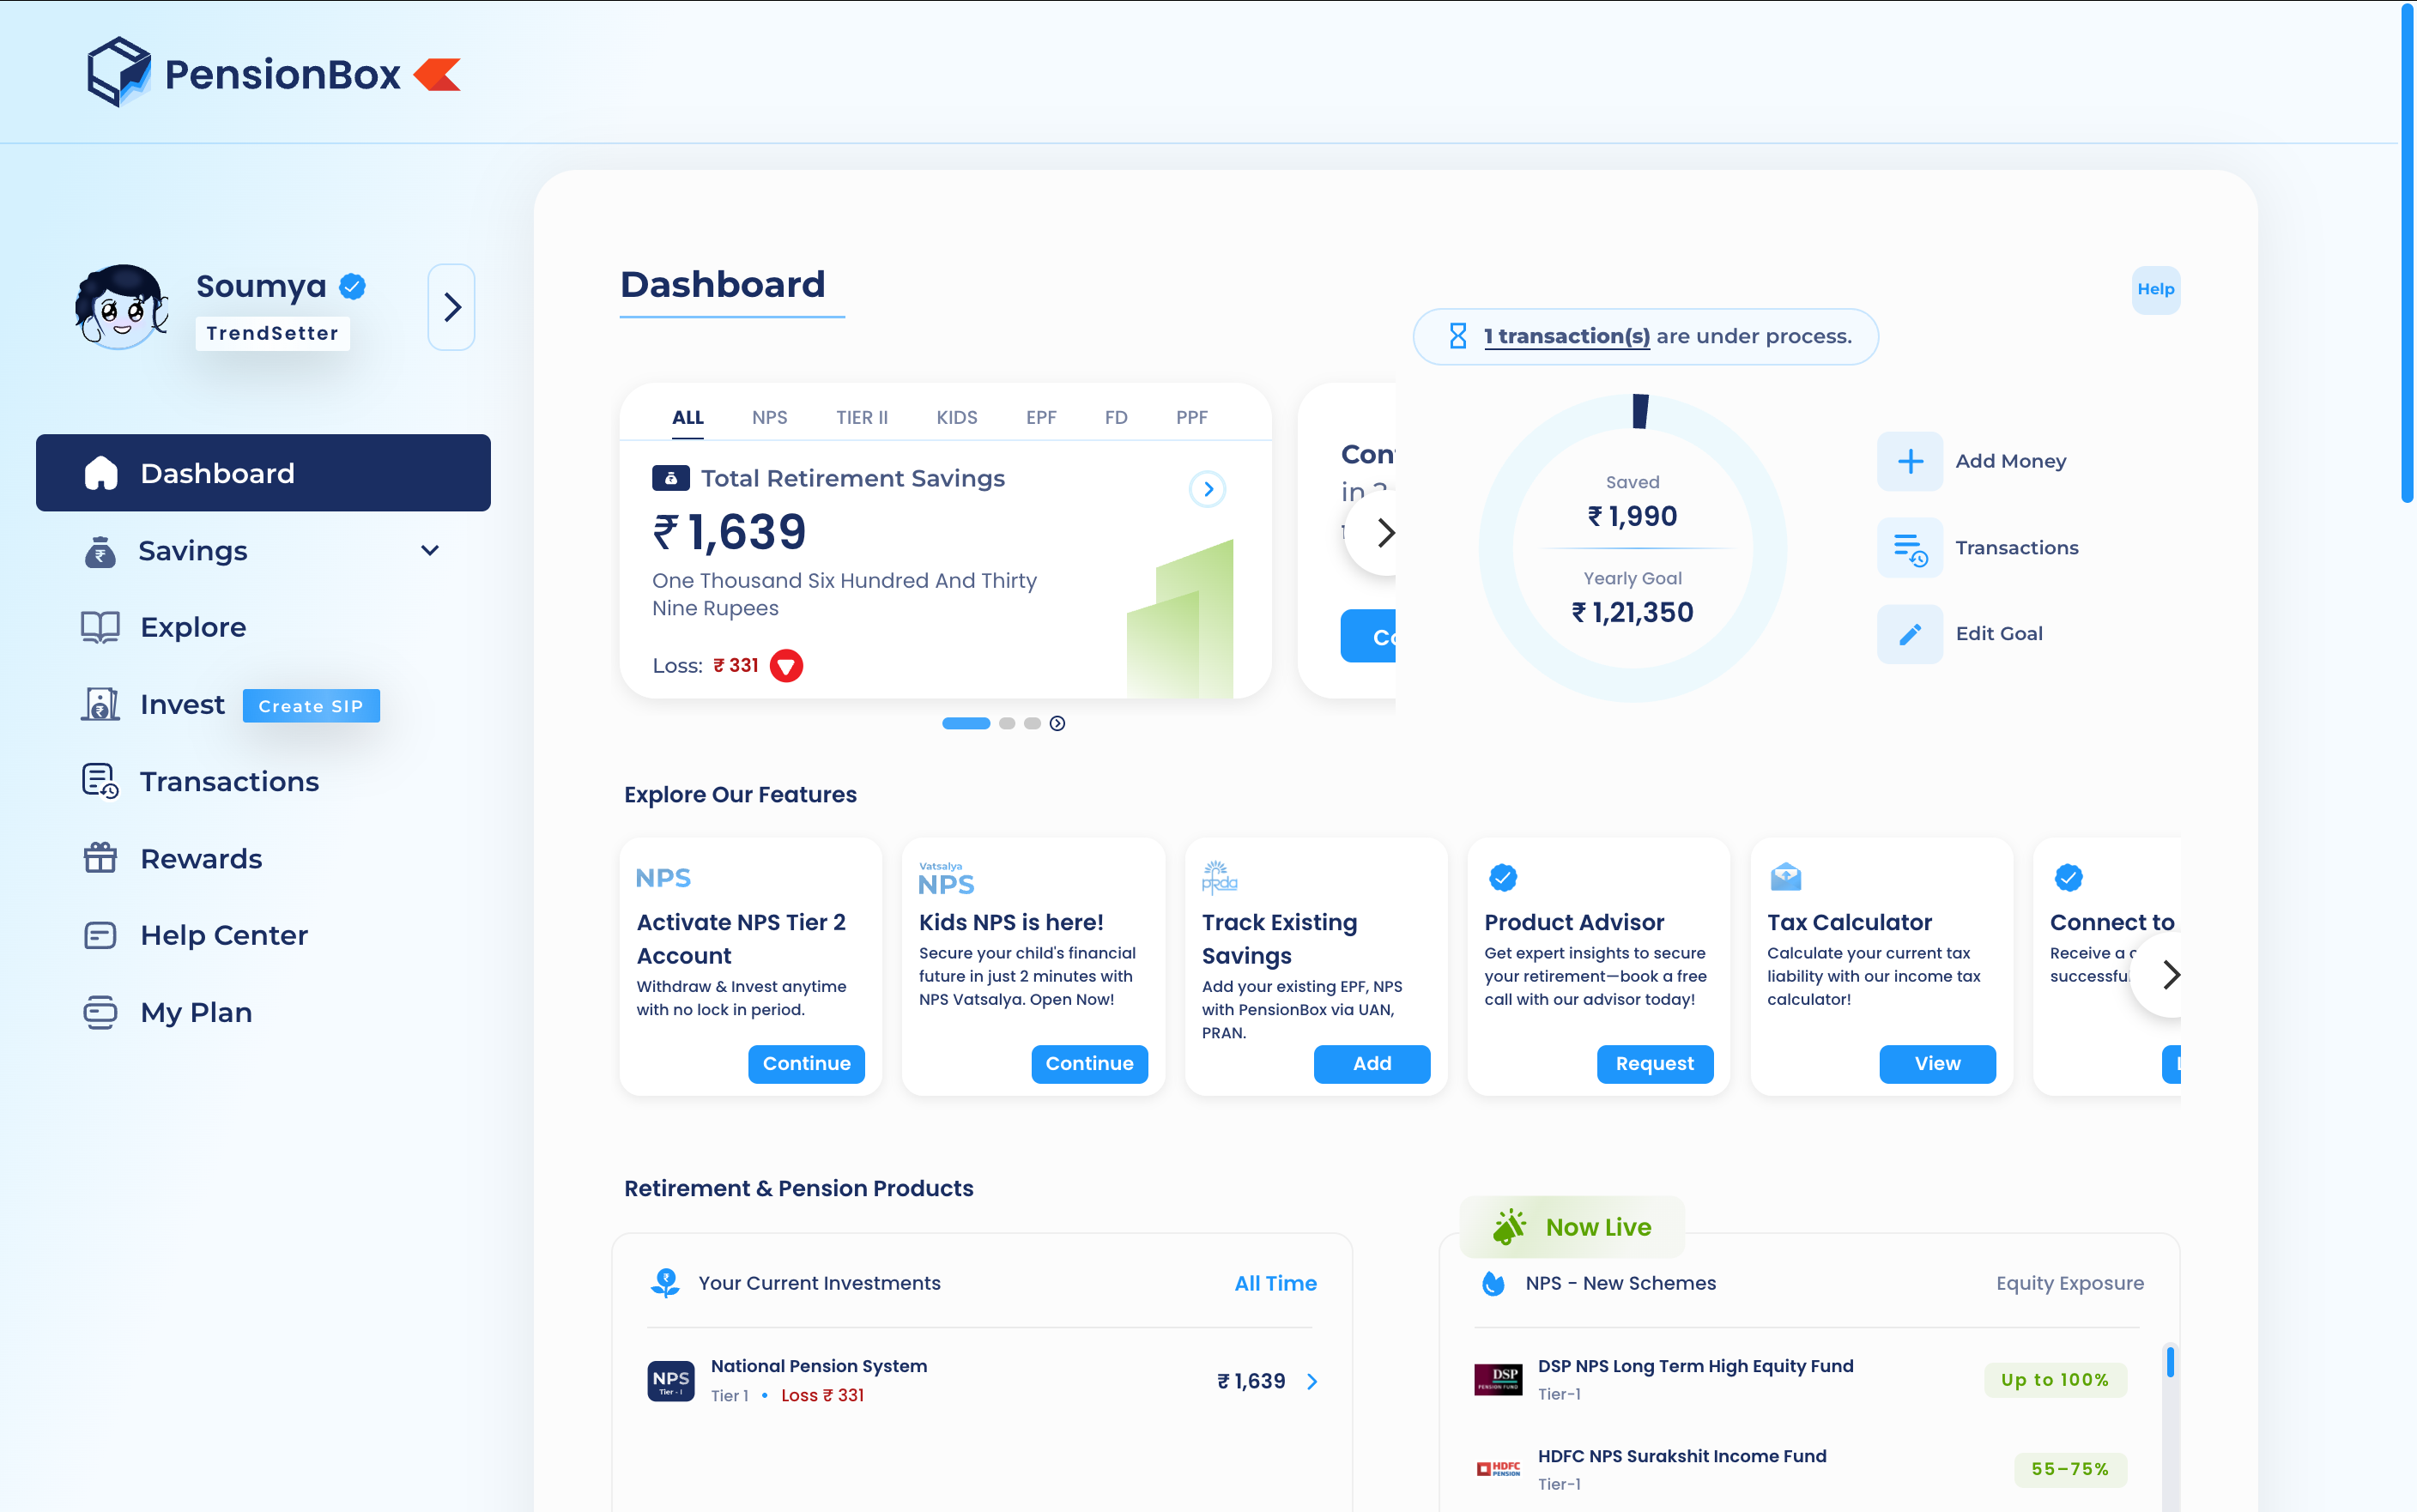
The PensionBox dashboard: your NPS account, SIPs and tracking in one place.
Who should shift and how comfortable is NPS after shifting? An example
An illustrative example.
A user has opened his NPS account on eNPS, but he keeps getting stuck on the CRA portal. He isn't sure where his money stands, he can't tell whether his SIP is set up correctly, and he worries about how withdrawal will work when the time comes. Here is how his everyday NPS moments change after he shifts to PensionBox (PoP: Zerodha):
| Aspect | eNPS | PensionBox |
|---|---|---|
| User Interface | Complex, multiple screens | Simplified dashboard |
| Support | Self-service | Dedicated support team |
| Account Tracking | Separate platforms | Unified tracking |
| Withdrawal Process | Unclear, independent | Guided assistance |
| Keeping track of EPF and other retirement products | Separate places to check | Tracked in the same app as NPS |
What does this ease cost him? On a ₹5 lakh corpus, the 0.20% PoP annual charge is about ₹1,000 a year before GST, roughly ₹83 a month. In return, a user gets a dashboard he understands, SIPs he can trust, and people to ask when he is stuck.
Want NPS to feel this comfortable? Shift your eNPS account to PensionBox and manage everything from one simple app, with a support team to help.
How to migrate your eNPS account on the PensionBox app
- Download the app and complete KYC. Sign up on the PensionBox app and finish your KYC.
- Enter your PRAN. If we detect that your account is an eNPS account, you'll be taken through a consent flow.
- Sign and request a call. Sign the consent and tap the request call option.
- Our support team completes the shift. A support executive will speak with you and process the shift from the back office. Refresh the app to see your updated account. Your PRAN, your corpus, your funds: all unchanged. Only the way you manage them gets easier.
Documents required
- Your PRAN
- Aadhaar and PAN
- A mobile number and email ID linked to your NPS account.
For further enquiries Contact us at: support@pensionbox.in, +91-8065588333
Frequently asked questions
Can I shift back to eNPS after migrating?
No. The move from eNPS to a PoP is one-way.
Do I need to visit a branch or fill out paper forms?
No. You start the request in the app, give consent digitally and request a call. Our support team completes the rest.
Do CRA and fund charges change when I shift to a PoP?
No. CRA charges (account maintenance and per transaction fees), fund management fees and NPS Trust charges apply to every NPS All Citizen account. Shifting adds PoP charges on top.
Can I switch PoPs later?
Yes. PoP-to-PoP shifting is allowed.
Is migration compulsory?
No. It's optional. Shift only if the added features are worth the charges to you.
2,00,000+ Stories
Hope they inspires you as well.

their NPS stories for a golden retirement.
PensionBox simplifies the National Pension System(NPS), the government's pension scheme for private employees both for retail users and HRs/companies.
If you don’t have an NPS account, you can simply open your pension account within 2 minutes and if you have NPS PRAN already, you will be able track, invest and manage everything free of charge with best user experience.
We never touch or hold your money directly, your investments go safely to your chosen pension fund through approved channels.
We are built with Zerodha as POP , ensuring transparency, data security, and peace of mind. Your retirement savings are protected by regulation and secured by technology.
That’s why, PensionBox brings transparency, zero charges, timely support and freedom to select any pension fund so that you get the best experience investing in NPS & be better future ready.
That’s not it, we help you & your company together to maximise contribution and tax savings with minimal charges & best user experience.
If you are an existing zerodha user then you get a fast login or sign up using kite ID.
Once you are onboarded with kite ID, you get free access to
- Open NPS in 2 minutes
- Track existing NPS
- POP shift or CRA shifting
- Invest in one time or create SIP in NPS
- Withdraw NPS requests & instant withdraw tier 2
- Create your dream retirement plan
- Open NPS Vatsalya for your kid
- Share with HR (To unlock more tax benefits)
- Employer Contribution:
- Contributions made by your employer to your NPS account are tax-free up to 14% of your basic salary under Section 80CCD(2). Do connect us with your HR to enable this for you.
Tax Benefits in Old Tax Regime - Self-Contribution:
- Deduction up to ₹1.5 lakh under Section 80C.
- Additional deduction of ₹50,000 under Section 80CCD(1B) — exclusive to NPS investments!
- This allows you to claim a total deduction of up to ₹2 lakh every year on your NPS contributions.
- Employer Contribution:
- Contributions made by your employer to your NPS account are tax-free up to 10% of your basic salary (Basic + DA) under Section 80CCD(2). Do connect us with your HR to enable this for you.
- This is over and above your personal deduction limits, giving you extra tax efficiency.
Feel free to book a free call to learn more about NPS, NPS Vatsalya, Corporate NPS & PensionBox or contact the support team.