Who Manages Your NPS Money: PFMs Explained
Planning for retirement involves more than saving money. It is equally important to understand how your savings are invested and who manages them.
The National Pension System (NPS) is a market-linked retirement savings scheme that helps individuals build a retirement corpus. An important part of NPS is choosing a Pension Fund Manager (PFM), the institution responsible for managing your investments.
Let's understand what PFMs do, who regulates them, the available options, and how to choose the right one for your retirement goals.
Who Are PFMs in NPS?
Pension Fund Managers (PFMs) are institutions registered with the Pension Fund Regulatory and Development Authority (PFRDA) to manage NPS investments. Think of them as the professionals who take the money you contribute to NPS and decide where to invest it.
When you contribute to NPS, your money is invested in asset classes such as equities, corporate bonds and government securities, depending on the scheme you choose. The PFM you select is the one that actually carries out these investments on your behalf.
Every PFM has its own investment team and its own approach. Even when two PFMs offer the same type of scheme (for example, an equity scheme), each may choose different companies or bonds, hold them in different proportions, and time its decisions differently, all within the limits set by PFRDA. Because of these differences, the returns of similar schemes can vary from one PFM to another, and the gap can change from year to year.
Remember: NPS returns are market-linked and are not guaranteed.
What Do PFMs Do, and Why Are They Needed?
PFMs manage the investment side of NPS and play an important role in growing retirement savings over time.
Their key responsibilities include:
- Managing investments: Investing NPS contributions across permitted asset classes.
- Making investment decisions: Selecting and managing securities according to the scheme's objectives.
- Following regulations: Complying with PFRDA's investment guidelines and applicable limits.
- Disclosing performance: Providing relevant portfolio and scheme information to help subscribers track their investments.
PFMs bring professional investment management to retirement savings, allowing subscribers to participate in the market without having to select individual securities themselves.
Who Regulates Pension Fund Managers?
The Pension Fund Regulatory and Development Authority (PFRDA) is the statutory regulator responsible for regulating and developing the NPS ecosystem in India. PFMs must be registered with PFRDA and comply with applicable regulations.
The NPS Trust also plays an important role in overseeing relevant aspects of the NPS framework and safeguarding pension assets.
For official information, visit PFRDA or NPS Trust.
Who Are the Existing PFMs in NPS?
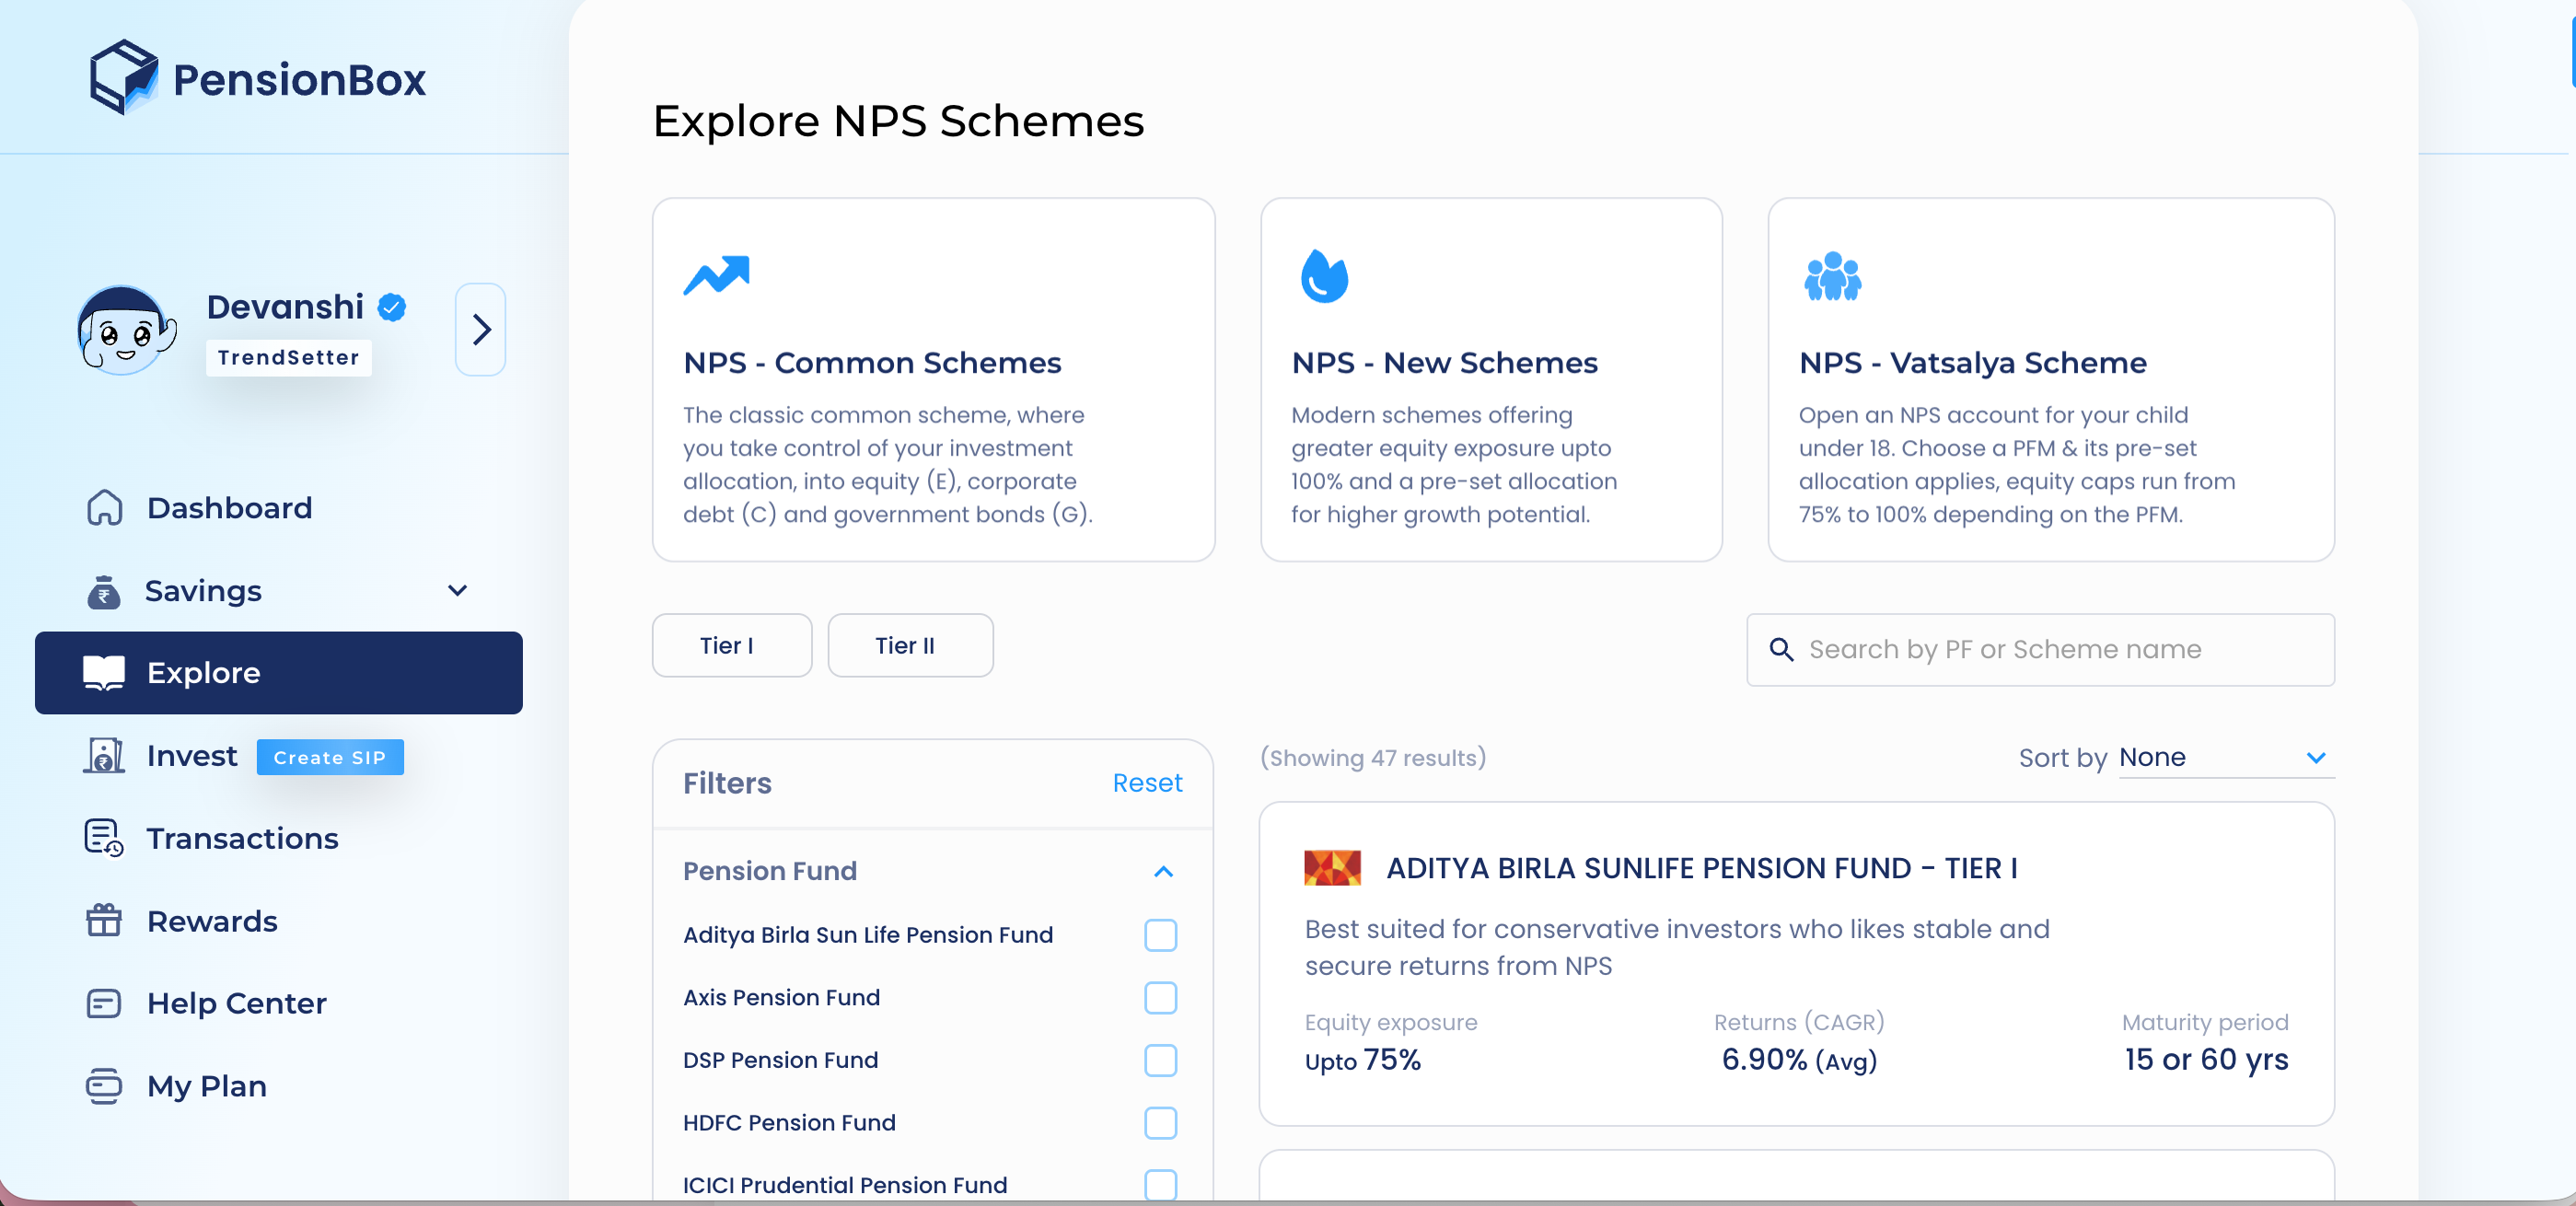
The registered Pension Fund Managers include:
- SBI Pension Funds Private Limited
- LIC Pension Fund Limited
- UTI Pension Fund Limited
- HDFC Pension Management Company Limited
- ICICI Pension Fund Management Limited
- Kotak Mahindra Pension Fund Limited
- Aditya Birla Sun Life Pension Management Limited
- Tata Pension Management Private Limited
- Axis Pension Fund Management Limited
- DSP Pension Fund Managers Private Limited
The availability of these PFMs may vary depending on the subscriber category and scheme.
Are new PFMs expected to join NPS?
PFRDA has approved four new sponsors to set up pension funds: Bank of Baroda, Bajaj Life Insurance, Motilal Oswal AMC and PPFAS (Parag Parikh). They aren't on the list above yet, so you can't choose them today. PFRDA now accepts applications at any time and allows banks to sponsor pension funds, so more names may follow.
What Should You Consider Before Choosing a PFM?
Choosing a PFM requires looking beyond short-term returns. Here are a few factors to consider:
- Long-term performance: Compare scheme-wise historical data over longer periods rather than relying on recent results alone.
- Investment strategy: Understand the scheme's exposure to equity, corporate debt and government securities.
- Risk tolerance: Consider how comfortable you are with ups and downs in your investment value and how soon you plan to retire.
- Portfolio composition: Review the asset classes in which the scheme invests.
- Your investment choice: Understand the different NPS investment options, including Active Choice, Auto Choice in the Common Scheme, and the Multiple Scheme Framework (MSF), to choose an approach that aligns with your retirement goals and risk appetite.
The right PFM is not necessarily the one with the highest recent returns. Your decision should align with your retirement timeline, financial goals and investment preferences.
What Are the Rules for Changing Your PFM?
NPS allows eligible subscribers to change their Pension Fund Manager (PFM), subject to the applicable rules.
Under the Common Scheme, subscribers can change their PFM once in a financial year. However, the rules under the New Scheme (MSF) do not allow for a change or shift from one PFM to another.
Want to understand how PFM changes work under the Common Scheme and MSF? Book a call with PensionBox to get guidance on the available options and make informed retirement planning decisions.
Before switching, keep the following in mind:
- Check your eligibility and the switching frequency applicable to your account.
- Confirm that your preferred PFM is available for your subscriber category.
- Understand how the change relates to your existing investment scheme and asset allocation.
- Follow the prescribed process through your CRA or other authorised channel.
For Corporate NPS subscribers, additional conditions may apply where the employer has selected the PFM or investment options. Check the relevant employer arrangement and current regulatory requirements before making changes.
A PFM switch does not guarantee higher returns, so review your investment goals and scheme performance before deciding.
How Can PensionBox Help You Get Started with NPS?
Understanding PFMs is an important step towards making informed retirement decisions. The next step is to explore your NPS options and begin planning for your future.
PensionBox helps make retirement planning more accessible by helping individuals understand NPS and navigate their pension-related choices.
You can open your NPS account through PensionBox and take the first step towards securing your retirement.
If your employer offers Corporate NPS, you can also learn how it works, how contributions are made and which investment options are available under your employer's arrangement.
Already have an NPS account? Track it at PensionBox and review your current PFM and investment scheme periodically and that can help you assess whether your choices are aligned with your retirement goals.
Frequently asked questions
How do I choose the right Pension Fund Manager for my NPS account?
When choosing a PFM, consider factors such as long-term performance, investment strategy, risk tolerance, and portfolio composition. Ensure that the PFM aligns with your retirement timeline, financial goals, and investment preferences rather than just the highest recent returns.
Can I change my Pension Fund Manager in NPS?
Yes, NPS allows subscribers to change their Pension Fund Manager once in a financial year, subject to applicable rules and conditions. Before switching, check your eligibility, confirm the availability of your preferred PFM, and understand how the change will affect your current investment scheme.
Who regulates the Pension Fund Managers in NPS?
The Pension Fund Regulatory and Development Authority (PFRDA) regulates Pension Fund Managers in NPS. PFMs must be registered with PFRDA and comply with its regulations to ensure the security and growth of your retirement savings.
2,00,000+ Stories
Hope they inspires you as well.

their NPS stories for a golden retirement.
PensionBox simplifies the National Pension System(NPS), the government's pension scheme for private employees both for retail users and HRs/companies.
If you don’t have an NPS account, you can simply open your pension account within 2 minutes and if you have NPS PRAN already, you will be able track, invest and manage everything free of charge with best user experience.
We never touch or hold your money directly, your investments go safely to your chosen pension fund through approved channels.
We are built with Zerodha as POP , ensuring transparency, data security, and peace of mind. Your retirement savings are protected by regulation and secured by technology.
That’s why, PensionBox brings transparency, zero charges, timely support and freedom to select any pension fund so that you get the best experience investing in NPS & be better future ready.
That’s not it, we help you & your company together to maximise contribution and tax savings with minimal charges & best user experience.
If you are an existing zerodha user then you get a fast login or sign up using kite ID.
Once you are onboarded with kite ID, you get free access to
- Open NPS in 2 minutes
- Track existing NPS
- POP shift or CRA shifting
- Invest in one time or create SIP in NPS
- Withdraw NPS requests & instant withdraw tier 2
- Create your dream retirement plan
- Open NPS Vatsalya for your kid
- Share with HR (To unlock more tax benefits)
- Employer Contribution:
- Contributions made by your employer to your NPS account are tax-free up to 14% of your basic salary under Section 80CCD(2). Do connect us with your HR to enable this for you.
Tax Benefits in Old Tax Regime - Self-Contribution:
- Deduction up to ₹1.5 lakh under Section 80C.
- Additional deduction of ₹50,000 under Section 80CCD(1B) — exclusive to NPS investments!
- This allows you to claim a total deduction of up to ₹2 lakh every year on your NPS contributions.
- Employer Contribution:
- Contributions made by your employer to your NPS account are tax-free up to 10% of your basic salary (Basic + DA) under Section 80CCD(2). Do connect us with your HR to enable this for you.
- This is over and above your personal deduction limits, giving you extra tax efficiency.
Feel free to book a free call to learn more about NPS, NPS Vatsalya, Corporate NPS & PensionBox or contact the support team.